Being ready to buy a home is not the same as wanting more space, finding an attractive listing, or receiving a preapproval. The real test is whether your finances and plans can absorb the purchase without turning every repair, bill, or life change into a crisis.
Before touring properties, estimate how much house you can afford using dependable income, existing obligations, and the full monthly cost of ownership. A price range should protect your flexibility after closing, not merely reflect the largest loan a lender might approve.
Mortgage Approval Is Not the Same as Readiness
A lender evaluates whether a mortgage fits underwriting standards. You must decide whether the payment fits the life you actually live.
The CFPB homebuyer readiness checklist separates reliable income, credit, debt, savings, mortgage capacity, and ownership expenses into distinct questions. One strong number cannot cancel every weak area. A large down payment does not stabilize unpredictable income, and a high credit score does not pay for a failed water heater.
Build a monthly budget that includes principal and interest, property taxes, homeowners insurance, possible mortgage insurance, association dues, utilities, maintenance, and existing financial goals. Then test whether you can still save after paying those costs.
A manageable payment should leave breathing room. If the budget only works when every month is perfect, the home is probably too expensive.
Stable Income Must Survive More Than a Good Month
Income readiness is less about reaching a particular salary than knowing what money is dependable. Commission earners, freelancers, seasonal workers, and business owners should build the budget around conservative earnings rather than peak months.
Ask what would happen if overtime disappeared, a client left, or one household member stopped working temporarily.
Employment plans matter too. A likely career change, relocation, return to school, or parental leave can alter income soon after closing. Do not treat a mortgage as affordable merely because today’s paychecks cover it.
A strong sign of readiness is that normal income covers the expected housing cost while irregular income remains available for savings or repairs. Bonuses should strengthen the plan, not rescue it.
Test the Mortgage Against a Lower-Income Scenario
A realistic affordability plan should include more than the household’s current monthly income. Buyers should calculate how the mortgage and other essential expenses would be handled during a weaker earning period, especially when part of the income depends on commissions, overtime, seasonal demand, or contract work.
This stress test does not require assuming the worst possible outcome. It means estimating the effect of a temporary income reduction and determining whether savings, reduced discretionary spending, or a second dependable income source could cover the difference without relying on credit cards.
Buyers should also review how consistently they have earned their current income. A recent raise or unusually profitable year may improve the present budget, but it may not yet prove that the higher earnings are sustainable. A longer record of dependable income creates a stronger foundation for ownership.
The safest mortgage payment is one that remains manageable when earnings are ordinary rather than exceptional. Leaving room below the household’s maximum capacity can protect retirement contributions, emergency savings, and other priorities when income changes after closing.
Savings Need to Cover the Purchase and the Aftermath
Many buyers focus so heavily on the down payment that they overlook money needed for inspections, closing expenses, moving, immediate repairs, utility deposits, furnishings, and prepaid housing charges.
The more important question is what remains afterward. Emptying savings to complete the purchase can leave a new owner exposed just as unfamiliar systems and maintenance needs begin to appear.
| Readiness Area | Stronger Signal | Warning Sign |
|---|---|---|
| Down payment | Saved without draining all reserves | Requires nearly every available dollar |
| Closing and moving | Estimated separately | Expected to come from leftover cash |
| Emergency savings | Remains accessible after closing | Falls close to zero |
| Repair capacity | Budget includes maintenance | Repairs would require new debt |
| Other goals | Essential savings continue | Home purchase pauses every priority |
There is no single reserve amount that suits every household. An older property, variable income, large insurance deductible, or single-income budget may justify a larger cushion. The goal is cash resilience after closing, not simply enough money to receive the keys.
Debt and Credit Reveal How Much Pressure You Can Carry
Credit affects mortgage access and pricing, while debt determines how much income is committed before housing costs begin. Review credit reports for errors, missed payments, high balances, or unfamiliar accounts before applying.
List every recurring obligation, including auto loans, student loans, credit cards, personal loans, and support payments. Fannie Mae’s guidance on understanding debt before applying for a mortgage explains how debt-to-income ratio can affect mortgage qualification and why reducing debt may strengthen a buyer’s financial position.
Do not reduce the analysis to whether a lender accepts your debt ratio. A technically acceptable ratio can still feel restrictive when childcare, medical spending, retirement contributions, or family support consume meaningful cash flow.
Paying down expensive revolving debt may improve both the application and the household budget. Avoid new obligations during the mortgage process because they can weaken affordability and complicate underwriting.
Lifestyle Plans Can Make a Good Loan a Bad Fit
Homeownership works best when the property supports reasonably stable plans. Consider how long you expect to remain in the area, whether the home can accommodate likely household changes, and how much maintenance you are willing to handle.
A buyer expecting to relocate soon may value flexibility more than ownership. Someone planning for children, remote work, aging relatives, or a new business may need a property and payment that can adapt.
Ownership also changes responsibility. Repairs can no longer be passed to a landlord, and selling requires time, expense, and uncertain market conditions. Readiness includes accepting those obligations, not just preferring ownership to renting.
Pressure Points That Mean You Should Wait
Waiting is often stronger when income is unstable, high-interest debt is growing, credit problems remain unresolved, or the purchase would consume nearly all savings. The same applies when a move, job change, separation, or major expense could reshape the budget.
Watch for emotional pressure. Fear of missing out can cause buyers to exceed their planned price, waive useful protections, or treat preapproval as permission to spend the maximum.
Test the budget by saving the difference between current housing costs and projected ownership costs for several months. If the amount remains manageable while other goals continue, the plan has evidence behind it. If the test repeatedly fails, it reveals a problem before the mortgage becomes permanent.
Ready to Buy a Home Means Ready for What Comes Next
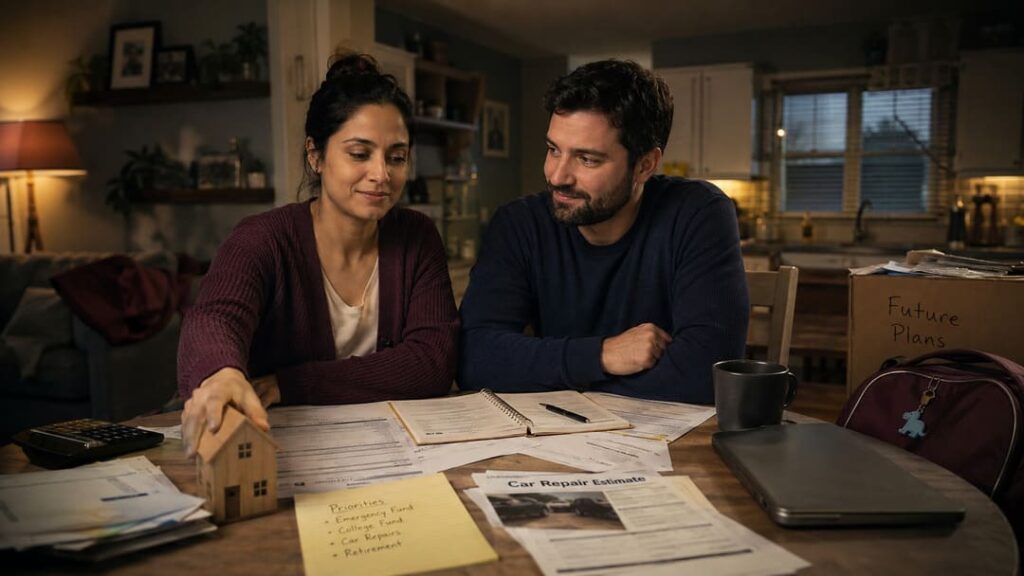
You are ready to buy a home when dependable income supports the full payment, savings survive the transaction, debt remains controlled, credit is prepared, and the property fits your likely plans. No single milestone proves readiness on its own.
The best opportunity is not buying as soon as you qualify. It is entering ownership with enough margin to handle repairs, changing costs, and ordinary life without regretting the purchase. A careful delay can strengthen your cash position and choices; a rushed closing can make an otherwise suitable home feel unaffordable.
FAQs
Is mortgage preapproval proof that I am ready to buy?
No. Preapproval estimates what a lender may allow you to borrow. It does not measure emergency savings, lifestyle plans, maintenance capacity, or whether the payment leaves room for other priorities.
How much savings should remain after buying a home?
The appropriate amount depends on income stability, property condition, insurance deductibles, household expenses, and repair risks. Buyers should avoid using every available dollar for the down payment and closing.
Should I pay off debt before purchasing a home?
Not every debt must be eliminated, but reducing high-interest balances can improve cash flow and mortgage readiness. Compare the benefit of debt repayment with the need to preserve adequate purchase and emergency savings.